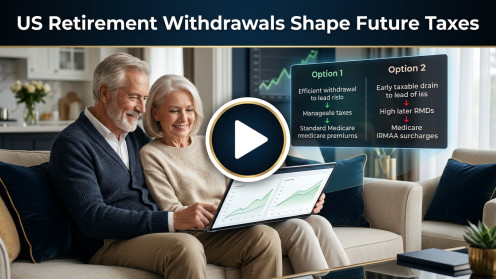
When it comes to retirement, the way you structure withdrawals can have a big impact on your future taxes and Medicare costs. Even with two retirees holding identical $2.1 million portfolios, the choices they make—like whether to pull from taxable savings or a traditional IRA—can lead to very different tax outcomes and Medicare surcharges down the road. For example, a portfolio split between taxable accounts and an IRA can generate $117,400 each year, but where you keep your assets affects both current efficiency and future tax pressure. For joint filers in 2026, keeping your Modified Adjusted Gross Income (MAGI) at or below $218,000 means you’ll stick with standard Medicare premiums, but go just one dollar over, and you could see Part B jump by nearly $284, plus additional Part D surcharges. Draining taxable accounts first may let your IRA grow, but this often results in larger required minimum distributions (RMDs) later on. Alternatively, making planned IRA withdrawals or conversions before you reach RMD age can help ease future tax and Medicare pressures. It's wise to model your RMD strategy before year’s end, avoid crossing into higher IRMAA brackets with conversions, and regularly review your IRA holdings for risks like floating rates, leverage, or high concentration. As someone licensed to help with Medicare and retirement planning, I know these decisions can feel overwhelming—but a thoughtful approach today can make a big difference for your peace of mind tomorrow.
Leave a Reply